
Below the SurfaceEnergy
Why "energy" shouldn't be reduced to oil majors or a sector ETF — five sub-sectors of the energy complex respond very differently to geopolitical supply disruption.
 Tom Fletcher, CFACo-Founder & Chief Investment OfficerMay 26, 2026 · 2 min read
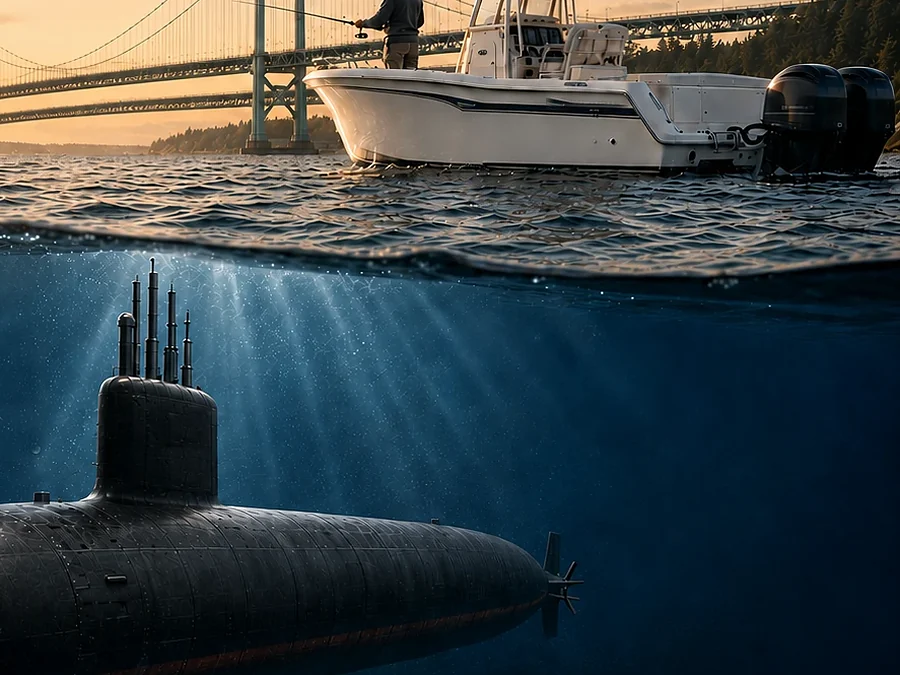
The power of going below the surface cannot be overstated. No, I am not trying to tout my submarine office service in the US Navy, I am pointing out that people generalize market views based on incomplete understanding within the market or sectors. Passive index management has had prolonged periods of outperforming the average active manager. I am not disputing the benefits of an economic investment solution or saying that ETFs or prominent large cap names in an index are a good or bad investment. What I am saying is that short-term opportunities are missed when that is as far as an investor looks.
A recurring question we have heard in recent weeks:
"With crude prices elevated amid heightened Middle East risk, why hasn't energy outperformed more?"
In my view, that question reflects an oversimplified framework.
How I Break Down the Energy Complex: Five Distinct Engines
In my experience, too often, "energy" is reduced to large cap integrated oil names (e.g., ExxonMobil) or broad sector ETFs (e.g., XLE). While these are convenient benchmarks, I believe they are incomplete representations of the underlying opportunity set.
- Upstream (Exploration & Production) — Company revenues and profits are closely tied to current and expected future oil and natural gas prices.
- Midstream — Volume- and contract-driven cash flows with infrastructure leverage. Less commodity-sensitive, more about throughput.
- Shipping (incl. Crude/Liquefied Natural Gas (LNG)/product tankers) — Crude, LNG, and product tankers are highly sensitive to dislocations in trade routes and logistics constraints. A re-routed barrel is often a more profitable barrel.
- Oilfield Services — Capex cycle exposure and operational intensity required to sustain shale production and discover new deepwater resources.
- Downstream & Chemicals — Margin-driven and often counter-cyclical depending on feedstock costs and end-user demand.
Why the Dispersion Matters Now
In periods of geopolitical stress, particularly scenarios involving supply disruptions or transit constraints (e.g., Strait of Hormuz risk), these segments do not respond uniformly. As a result, top-down observations (sector indices, integrated majors) can materially understate the dispersion within the complex.
Several components of the energy ecosystem currently exhibit characteristics more consistent with targeted hedges than simple commodity beta:
- Exposure to physical bottlenecks and rerouting dynamics
- Sensitivity to duration of disruption, rather than just spot price levels
- Resilience—or in some cases positive convexity—in risk-off or USD-strength environments
Additionally, the oil forward curve continues to price a relatively orderly normalization of supply. To the extent that disruption proves more persistent, there is potential asymmetry embedded in carry and term structure positioning. In my view, this positioning could act as a hedge against global disruption, with the potential to earn income while it is held.
IMPLICATION
Benchmarking "energy" through integrated majors or broad ETFs is directionally useful but may be strategically insufficient. Capturing the opportunity set requires a more thoughtful and nimble allocation framework, focused on asymmetric upside to dislocations rather than where energy market beta is most visible.
Our perspective, May 26, 2026. The opinions here reflect market conditions at that time and may have changed.
Tom Fletcher brings more than two decades of institutional investment leadership to GenSphere, combining experience in portfolio management, investment implementation, and risk management with a disciplined understanding of how capital serves long-term objectives.
View Biography →