
Before the Offer: The Questions to Answer First
The owners who keep the most are rarely the ones who negotiated hardest. They are the ones who did the boring work early, while there was still room to move.
 Ryan Halleran, JD, CAP®Co-Founder · Advanced PlanningJune 18, 2026 · 3 min read
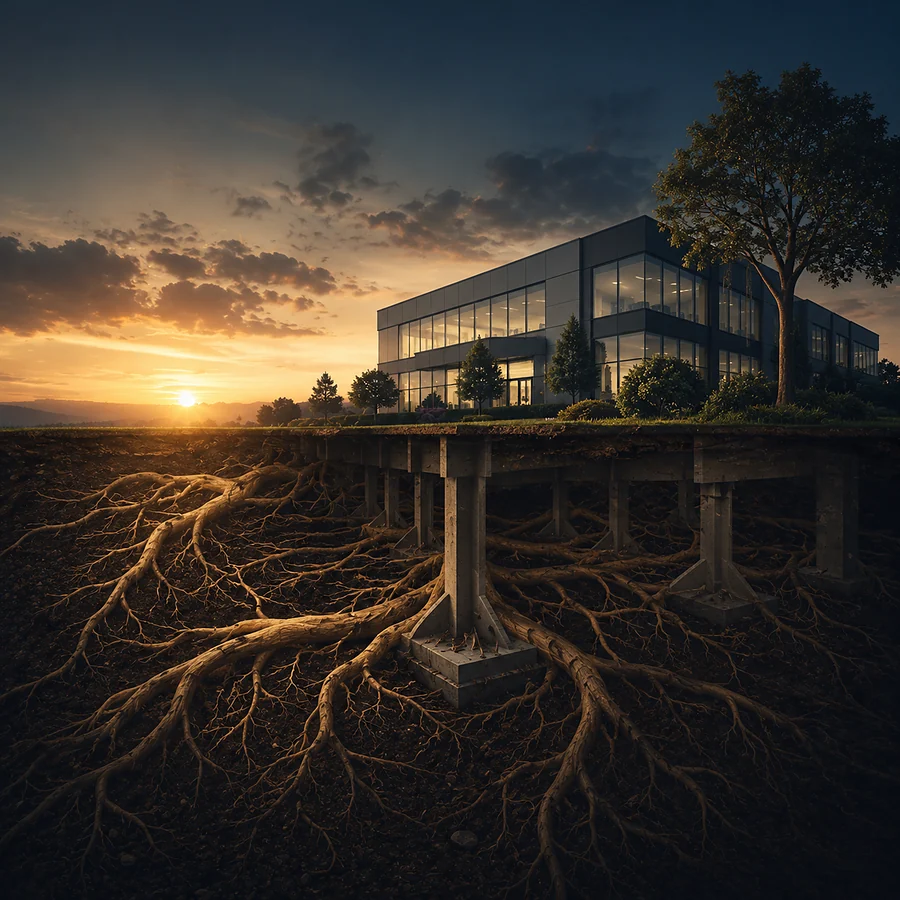
By the time a letter of intent is on the table, most of the decisions that determine what you keep have already been made — or already been missed. This series is about the window before that, when the choices are still yours.
I spend much of my time beside business owners in the eighteen months before they sell, and beside the ones who wish they had called eighteen months earlier. The second group is larger. By the time an offer arrives, the deal has a momentum of its own, and momentum is a poor time to do tax and estate planning.
The most expensive decisions are made before the bankers show up.
A sale looks like a single event. It is really the last in a long series of smaller choices — how the entity is structured, who owns what and in what form, whether shares were moved into trust years ago or are sitting in your name today. Those choices set the tax and estate outcome long before anyone negotiates a price. Once the offer is real, most of them are frozen. You are no longer planning; you are reacting. The owners who keep the most are rarely the ones who negotiated hardest. They are the ones who did the boring work early, while there was still room to move.
Three things worth settling while you still can
Where the equity lives. Moving ownership — into a trust, to the next generation, to a charitable vehicle — is far more powerful before a valuation event than after. Once a buyer puts a number on the business, the gift you wanted to make has become more expensive, sometimes by a multiple. The cheapest time to move an asset is before the market tells everyone what it is worth.
What the sale is actually for. I ask every owner the same question early: what is this money supposed to do? Fund a retirement, seed the next venture, care for a family member, build a legacy? The answer changes the structure. A deal designed for liquidity looks different from one designed for legacy, and you cannot optimize for a goal you have not named.
Who is on your side of the table. A clean sale runs on coordination — the banker, the M&A attorney, the CPA, and the wealth side all moving in the same direction. When they do not talk, things fall through the cracks at the worst moment: a tax election missed, a representation no one flagged, a closing that slips. My job is often simply to keep everyone aligned so the deal closes cleanly and the owner is not the one chasing it.
The part nobody puts in the model
For most owners, the business is not just an asset. It is identity, routine, and standing in a community, built over decades. Selling it changes more than a balance sheet. The owners who come through a sale happiest are the ones who planned for the day after the wire hits, not just the wire itself. We plan for that side too, because it is usually the side that surprises people.
What this series is for
Over the coming quarters I will write about the structures that matter most before a sale, the mistakes owners make under deal pressure, how to work with an investment banker without losing the planning thread, and what the smartest owners do in the quiet years before anyone is thinking about an offer. The offer will take care of itself. It is everything before the offer that decides how the story ends.
Ryan Halleran brings extensive experience in advanced wealth planning, business transitions, estate strategy, and succession considerations to GenSphere.
View Biography →Related briefings
Top of Mind
Bring the decision you are facing.We will start there.
Starting from: Business Transaction